

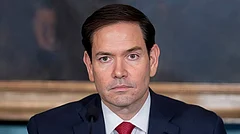
US Secretary of State Marco Rubio’s October 21, 2026, visit to Jamnagar underscored energy’s growing role in India-US relations.
Rubio’s call for India to diversify its energy imports can also be seen as an appeal to buy more Venezuelan oil, which the US firmly controls, and to pull India away from Russian energy linkages.
India must use Jamnagar’s industrial capabilities and its purchasing power to secure reliable supplies at competitive prices.
US Secretary of State Marco Rubio’s October 21, 2026, visit to Jamnagar underscored energy’s growing role in India-US relations. For Washington, India offers a vast market and advanced refining capabilities. For New Delhi, the test is whether closer cooperation delivers reliable, affordable supplies or adds to the economic burden of energy dependence.
Diversification And Its Price
Before visiting Jamnagar, Rubio identified greater processing of Venezuelan crude and possible Reliance participation in Venezuelan production as subjects for discussion. However, his call for India to diversify its energy imports can also be seen as an appeal to buy more Venezuelan oil, which the US firmly controls, and to pull India away from Russian energy linkages.
Expanded energy trade brings America revenue and leverage while diversifying India’s supplies. However, costlier imports can undermine these benefits by pressuring the rupee, raising inflation and weakening investment and growth.
American liquefied natural gas (LNG) shipments to India have already risen substantially. According to US Energy Information Administration data, monthly volumes averaged roughly 0.2 million tonnes in January-February 2026, before the West Asia conflict, but climbed to around 0.75 million tonnes during March-July 2026—about 3.4 times the earlier level.


Disrupted Gulf supplies forced India to buy costlier replacement cargoes. According to data from the Petroleum Planning and Analysis Cell (PPAC), India’s LNG import bill was about $1.2 billion in September 2026. With import volumes slightly lower than a year earlier, this implied an average procurement cost of roughly $550 per tonne—still around 10 per cent above pre-war levels of about $500 per tonne. Spot cargoes purchased for September delivery were substantially costlier, with some deals reported at roughly $1,200 per tonne.
US-linked replacement cargoes were estimated to cost $100-150 per tonne more than pre-war Qatari contract supplies, although comparable post-war delivered prices across suppliers remain limited. Any premium must therefore be weighed against measurable gains in supply reliability and long-term affordability.

Refining Gains And The Import Burden
Jamnagar provides negotiating leverage, export earnings and industrial value addition. Refinery revenues must be distinguished from profits, as much of the income covers imported crude: illustratively, a $100 barrel may yield a $10 margin before operating expenses.
PPAC’s September 2026 snapshot puts LNG imports at $1.2 billion, despite volumes falling 8.5 per cent year-on-year, implying approximately $550 per tonne, around 10 per cent above pre-war levels.
Spot purchases were substantially more expensive. Bloomberg reported that Gas Authority of India Limited and the Gujarat State Petroleum Corporation’s September-delivery spot purchases at approximately $1,150-1,200 per tonne. Rupee depreciation raises domestic costs, compounded by regasification, pipeline transport and taxes paid by consumers and industry.
With imports meeting 88 per cent of crude requirements, India remains exposed to global prices. Even after petroleum-product export earnings, the net oil and gas import bill rose from $60 billion in April-September 2025 to $81 billion a year later. Refining gains therefore offer only a partial cushion against expensive energy imports.

Pressure On The Rupee And Growth
A higher energy bill increases demand for dollars. Unless stronger exports, remittances, or capital inflows match it, it increases external financing needs and puts pressure on the rupee. Depreciation then raises the domestic cost of dollar-priced imports, reinforcing the original shock.
Capital outflows compound this vulnerability. The Reserve Bank of India (RBI) data show net foreign portfolio investment recorded an outflow of $9.6 billion in April-June 2026, versus a net inflow of $1.6 billion a year earlier. Global uncertainty and higher returns on dollar assets can encourage further withdrawals and discourage fresh inflows. India therefore faces pressure from both rising import-related demand for dollars and portfolio outflows. The depletion of foreign exchange reserves is an additional concern; reserves have fallen by roughly $50-60 billion from their early-September peak, reflecting the central bank’s interventions to steady the rupee.
The domestic consequences are equally significant. Higher energy prices raise transport, manufacturing and fertiliser costs. Passing on these cost increases erodes household purchasing power, while absorbing them squeezes corporate margins and discourages investment. Government support can cushion the immediate shock, but it adds to fiscal pressure.
The RBI’s recent repo rate hike to 5.5 per cent raises borrowing costs when inflation is largely supply-driven. Monetary tightening can neither remedy energy shortages nor reduce international fuel prices. Rather, it raises working-capital costs for businesses and restrains consumption and investment, risking slower growth while external pressures remain unaddressed. Central banks often raise rates even in such episodes to limit second-round effects and keep inflation expectations anchored, but the primary remedy still lies outside monetary policy.
India thus faces a difficult trade-off: containing inflation without deepening the slowdown caused by expensive energy. Prolonged supply pressures, compounded by tighter credit, could weaken investment, employment and growth while keeping prices elevated. This creates a risk of stagflationary pressure.
Affordability Must Guide Energy Diplomacy
India-US relations are strategically vital to India. Yet the increasingly transactional character of American diplomacy, shaped by geopolitical interests, requires New Delhi to pursue energy cooperation with commercial prudence rather than euphoria, preserve established supply networks, and strengthen domestic production, energy efficiency and strategic reserves.
India must use Jamnagar’s industrial capabilities and its purchasing power to secure reliable supplies at competitive prices. Affordability is central to energy security—and must remain central to its energy diplomacy.
(The author is a former diplomat and economist. He is the author of the book ‘Energy Security and Economic Development in India: A Holistic Approach’)
(Views expressed are personal)